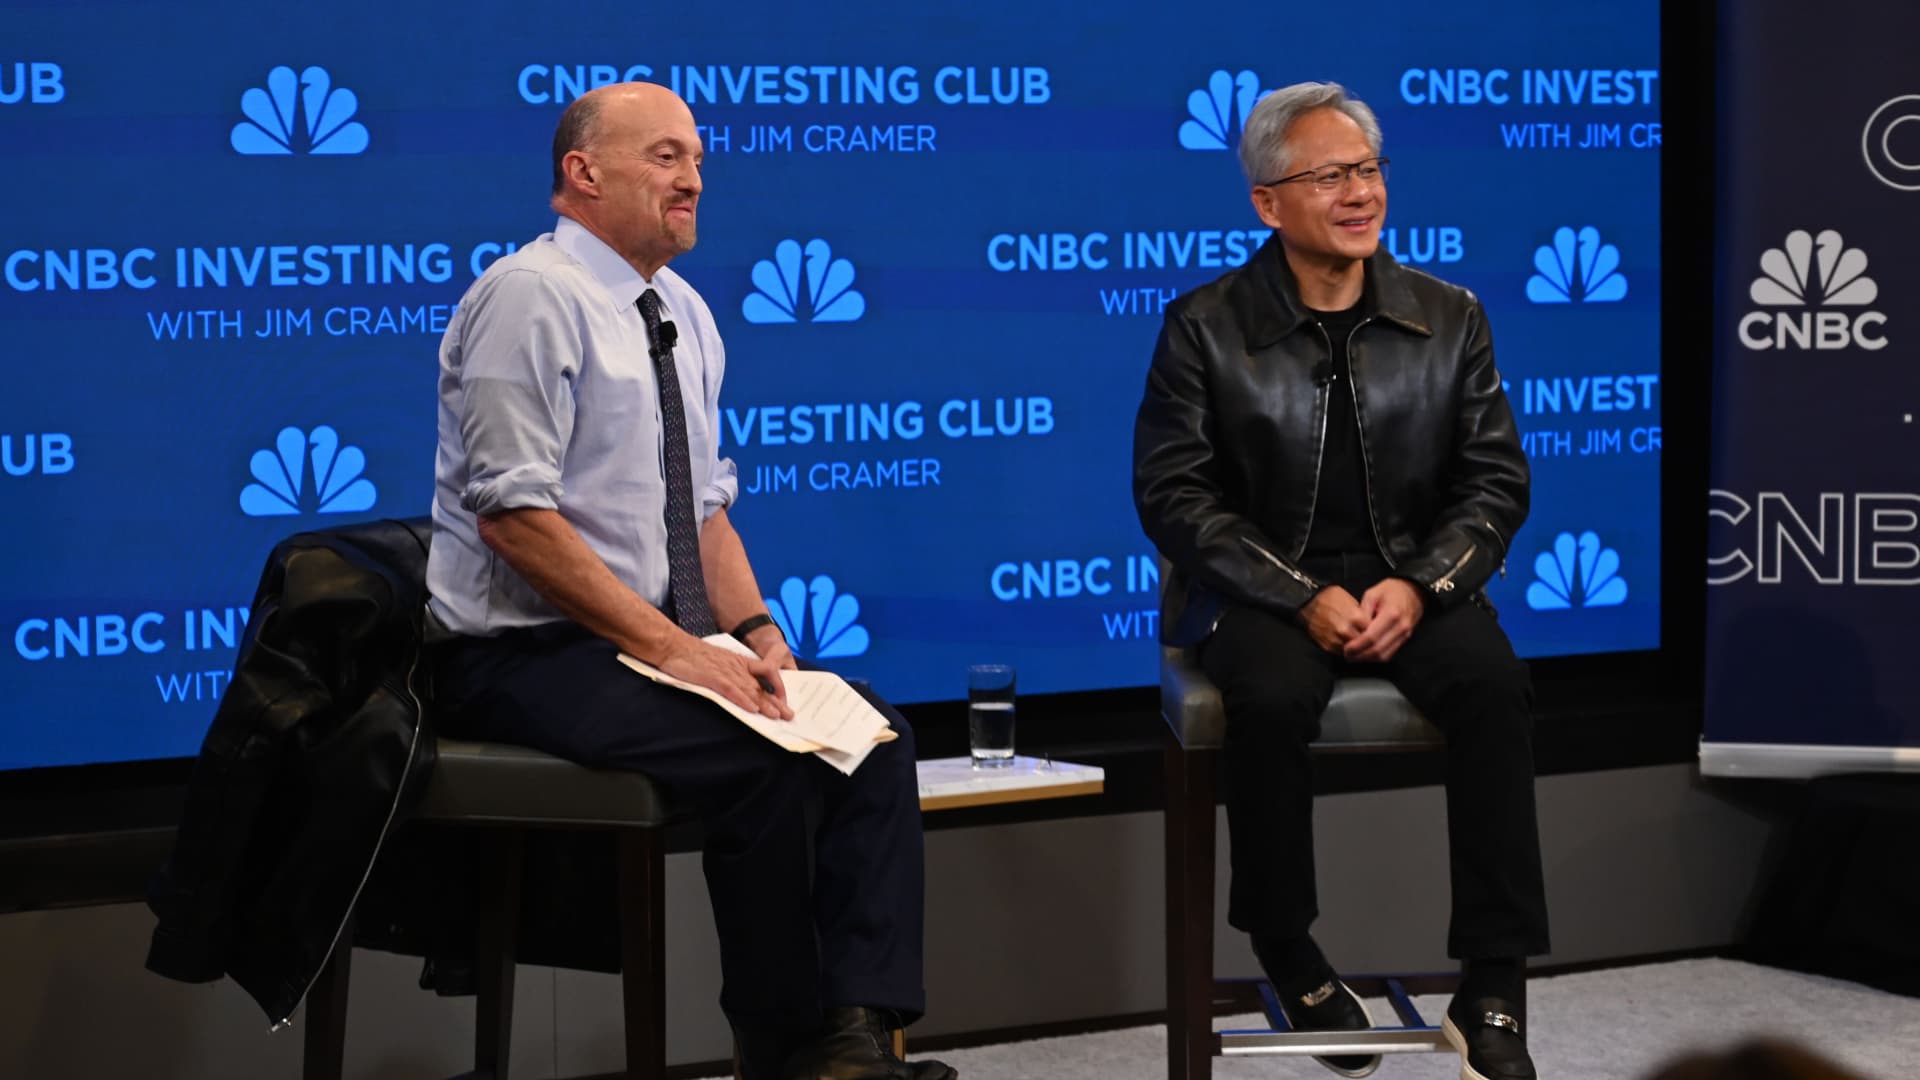
Jim Cramer’s argument for Nvidia rests on a striking claim: investors are paying unusually little for its expected profits. On November 5, the CNBC host described its earnings multiple as the lowest in about a decade, citing a figure of 16.5, according to 24/7 Wall St.’s account of his remarks. Coverage of Cramer’s valuation claim
The market has been less convinced. Nvidia fell about 9% on November 5 during a broader technology selloff, then recovered nearly 3% on November 6. Reuters on Thursday’s selloff · Reuters on Friday’s rebound
The disagreement centres on how much confidence to place in future earnings. Strong demand for AI chips can support a bullish valuation. Delayed data centers, more expensive components and customers’ financing needs can change when that demand becomes profitable revenue.
A low earnings multiple makes that question more consequential. It does not settle it.
What “cheap” means in Cramer’s argument
A price-to-earnings ratio divides a company’s share price by earnings per share. A forward P/E uses expected earnings, so the result depends on both today’s price and a forecast.
The earnings period matters. Estimates for the next 12 months, the current fiscal year and the following fiscal year can produce substantially different ratios. So can using reported accounting earnings rather than adjusted earnings.
Cramer’s reported 16.5 figure should therefore be treated as his valuation assessment at the time. Independently establishing a decade-low multiple would require a historical series using a consistent earnings definition and forecast period.
The underlying sensitivity is straightforward. Start with a hypothetical stock valued at 16.5 times forecast earnings and keep its share price unchanged:
| Earnings outcome relative to the original forecast | Resulting P/E |
|---|---|
| 20% above forecast | 13.8 |
| Meets forecast | 16.5 |
| 20% below forecast | 20.6 |
| 40% below forecast | 27.5 |
Illustrative calculation, not a forecast for Nvidia. Divide 16.5 by the proportion of forecast earnings delivered: for a 20% shortfall, 16.5 ÷ 0.8 = 20.625.
The share price has not changed in this example, yet the apparent bargain becomes less compelling as earnings fall short. Better-than-expected earnings work in the opposite direction.
That is the issue investors need to resolve: how dependable is the profit forecast underlying the multiple?
Nvidia’s latest results support the bullish case
Nvidia’s business was still growing rapidly in its most recent reported quarter. For the quarter ended July 26, 2026, the company reported $96.2 billion in revenue, up 106% from a year earlier. Data Center revenue reached $89 billion, up 117%, and its GAAP gross margin was 75%.
Its August outlook called for third-quarter revenue of $108 billion, plus or minus 2%. That was management’s forecast, with no China Data Centre compute revenue assumed. Nvidia’s second-quarter results and outlook
These figures explain why a falling share price can attract buyers. If revenue and profits continue growing strongly, investors obtain those future earnings at a lower purchase price.
But a stock can fall while its latest results remain strong. Investors also assess what comes after the reported quarter, how much growth they previously expected and how much risk they now attach to it.
The risks extend beyond demand for AI chips
Data centers need permission, power and financing
Reuters linked the November 5 selloff to fears that Democratic election victories could bring greater scrutiny of data center development. Its reporting also identified financing pressure on specialized AI cloud providers and local opposition over electricity and water use. These were concerns about future expansion, rather than evidence that the election had already cancelled Nvidia’s orders. Reuters’ analysis of the AI selloff
The practical connection is simple. A customer needs somewhere to install and operate the equipment it wants to buy. Nvidia’s quarterly filing itself identifies land, power, buildings and capital as constraints that could affect deployments and revenue. Nvidia’s quarterly risk disclosures
A project delayed by several quarters can still be commercially viable. However, shifting its purchases into a later period can weaken the near-term earnings forecast used to value its suppliers.
Growth Presto’s examination of the midterms’ economic consequences explores the wider debate over data center development and the costs borne by surrounding communities.
Higher sales do not guarantee stable margins
On Nvidia’s August earnings call, finance chief Colette Kress warned about rising memory costs. Management expected gross margins to bottom at 71%–72% in the fourth quarter of fiscal 2027, before reaching 72%–73% in fiscal 2028 as price increases took effect. Nvidia’s earnings-call transcript
These are forecasts, including the recovery. Rising costs reduce gross profit per dollar of sales unless pricing or efficiencies compensate. Sales can still grow fast enough to lift total profits.
Financing customers adds another source of exposure
On the same call, Nvidia said it had invested nearly $50 billion in frontier AI laboratories and described selective credit support for another lab’s infrastructure. Management defended the approach as investment in promising businesses and argued that its computing equipment could be redeployed to other customers. Management’s explanation of its AI investments
This can help customers expand and buy equipment. It also makes their financial strength relevant beyond the next chip order. Can their revenues sustain further purchases, and what happens to Nvidia’s investments if their plans fall short?
Nvidia is also committing resources ahead of demand. Its July filing disclosed $279 billion in supply and capacity commitments, up from $119 billion the previous quarter. These extend across several years; some arrangements can be adjusted, potentially at additional cost. Supply and capacity commitments
Securing production helps when demand arrives as expected. It creates greater exposure to mismatches when customers change their plans.
Cramer’s buyback call needs a separate test
Cramer also urged Nvidia to repurchase shares during the decline. Benzinga’s November 5 coverage records his argument that the company should put its authorized buyback capacity to work. This was a call for Nvidia to buy its own stock. Cramer’s buyback comments
On September 28, Nvidia authorized an additional $150 billion in repurchases, bringing its remaining program to $235 billion at that date. It said it expected to execute the program through fiscal 2028. Nvidia’s buyback announcement
That authorization does not establish how much Nvidia bought on a particular trading day. It’s a July-quarter filing document for $39.8 billion of repurchases in the first half of fiscal 2027 but covers a period ending well before November’s selloff. Disclosed repurchase spending
Repurchases can increase earnings per share by reducing the share count, all else equal. They also consume cash. Their value depends on the price paid and the returns available from other uses of that money.
The relevant evidence will be actual purchases and the resulting share count. The size of an authorization alone cannot establish that management supported the stock during this decline—or that the stock has found a floor.
What November 17 needs to clarify
Nvidia has scheduled its third-quarter results for November 17, followed by an analyst call at 5 p.m. Eastern time. Nvidia’s results announcement
The report will provide several tests of the competing arguments:
- Revenue and the next outlook: whether deliveries support continued growth or customers are shifting purchases into later quarters.
- Margins: whether component costs and pricing are developing as management expected.
- Cash generation and customer support: how effectively sales become cash, and whether financing exposure is increasing.
- Buyback execution: what Nvidia actually spent during the reported quarter, rather than the amount it was permitted to spend.
Results for a quarter ending October 25 will not, by themselves, reveal purchases made during the November selloff.
Cramer’s case becomes stronger if Nvidia delivers the earnings that make its valuation look modest. The cautious case strengthens if delays, costs or financing problems reduce those earnings. The next useful number is therefore the profit Nvidia can sustain—and how it compares with the forecast investors are using today.